


British Pound sees more downside as US Yields rally further
- The British Pound declines to near 1.3225 against the US Dollar.
- Fed’s Williams said it is reasonable to expect more interest rate hikes this year.
- BoE’s Lombardelli and Dhingra share contrary views on economic activity.
The British Pound (GBP) is down 0.12% to near 1.3225 against the US Dollar (USD) during the European trading session on Thursday. The GBP/USD is under pressure and might face more decline as United States (US) Treasury Yields rally further amid firm expectations that the Federal Reserve (Fed) will hike interest rates again this year.
In European trade, 10-year US Treasury Yields post a fresh 19-year high at 5.15%. Surging US Treasury Yields have strengthened the US Dollar too. As of writing, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades 0.15% higher to near 101.32, the highest level seen in eight weeks.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the strongest against the Swiss Franc.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.08% | 0.10% | 0.25% | 0.09% | 0.13% | 0.06% | 0.26% | |
| EUR | -0.08% | 0.01% | 0.18% | 0.02% | 0.04% | -0.04% | 0.16% | |
| GBP | -0.10% | -0.01% | 0.17% | -0.04% | 0.01% | -0.05% | 0.15% | |
| JPY | -0.25% | -0.18% | -0.17% | -0.20% | -0.13% | -0.24% | -0.03% | |
| CAD | -0.09% | -0.02% | 0.04% | 0.20% | 0.06% | -0.05% | 0.17% | |
| AUD | -0.13% | -0.04% | -0.01% | 0.13% | -0.06% | -0.09% | 0.12% | |
| NZD | -0.06% | 0.04% | 0.05% | 0.24% | 0.05% | 0.09% | 0.24% | |
| CHF | -0.26% | -0.16% | -0.15% | 0.03% | -0.17% | -0.12% | -0.24% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
The CME FedWatch tool shows an almost 55% chance that the Fed will hike interest rates in both remaining policy meetings this year.
Fed board members have also warned of more interest rate hikes this year as high inflation is proving to be a key challenge.
Williams flags resilience and AI demand while keeping door open to another Fed hike
Fed’s Williams delivered a speech that scored 7.2/10 on the FXS Speechtracker, notably above the 6.2/10 historical average, underscoring a tone that remains firmly focused on the inflation challenge despite acknowledging that downside risks to maximum employment have receded and that the US economy shows “remarkable resilience.” The emphasis on “pretty strong demand from AI,” the need to get inflation back to target in a “timely manner,” and the remark that it is “reasonable to see another rate hike by end of year,” even as explicit forward guidance is dialed back and uncertainty around the persistence of higher yields is admitted, collectively point to a cautious but still hawkish policy stance that should underpin the Dollar on balance.
The FXS Fed Sentiment Index slipped by 0.18 points to 148.63, signaling a modest pullback in perceived hawkishness even as the index remains deep in hawkish territory well above the neutral 100 mark. This configuration suggests that, relative to the established baseline, the market reads Williams as slightly less hawkish at the margin, but still clearly aligned with a Fed bias that keeps further tightening on the table and supports the Dollar against lower-yielding peers.
On the Pound Sterling front, Bank of England (BoE) officials share contrary views regarding the monetary policy outlook.
BoE’s Lombardelli flags conditional tightening bias as energy risks persist
BoE Deputy Governor Clare Lombardelli scores 8.4/10 on FXS Speechtracker, exactly in line with the speaker’s historic average, pointing to a consistently hawkish profile rather than a fresh surprise. The emphasis that policy is “increasingly likely to need to tighten” if elevated energy prices persist, combined with the view that wage growth is still too high for the inflation target, reinforces a clear tightening bias even while acknowledging that monetary policy should not react mechanically to energy price swings.
The speech underscores that Bank Rate remains restrictive but could rise further if the interaction between the underlying economy and higher energy costs sustains inflation, marking a marginally more hawkish tilt versus the current stance. For GBP, the conditional tightening language and focus on wage-driven persistence in inflation support expectations of higher-for-longer rates, which is typically supportive for the currency, while the stress on data dependence and demand risks tempers the upside by keeping the path of future moves explicitly contingent on incoming activity and disinflation signals.
Contrary to BoE's Lombardelli who supported the need of interest rate hikes if energy prices remain elevated, BoE policymaker Swait Dhingra said there are evidence of easing price pressures and weakness in the United Kingdom (UK) labour market.
BoE’s Dhingra speech scores 3.2/10 on FXS Speechtracker, exactly in line with the speaker’s historic average, signalling no meaningful shift in overall tone. Emphasis that UK financial conditions have already done “a lot of tightening work,” alongside a “pretty weak” labour market and concern over winter energy prices, leans the message toward a cautious, growth-sensitive stance that is mildly dovish for GBP.
At the same time, encouragement about current pricing and the absence of broad-based price rises like in 2022 suggest reduced inflation persistence, reinforcing the case against further aggressive tightening. The focus on second-round effects from winter energy prices keeps a conditional inflation risk on the radar, but the balance of remarks points to a BoE that is more inclined to wait and watch than to push GBP higher via additional rate hikes.
GBP/USD Technical Analysis
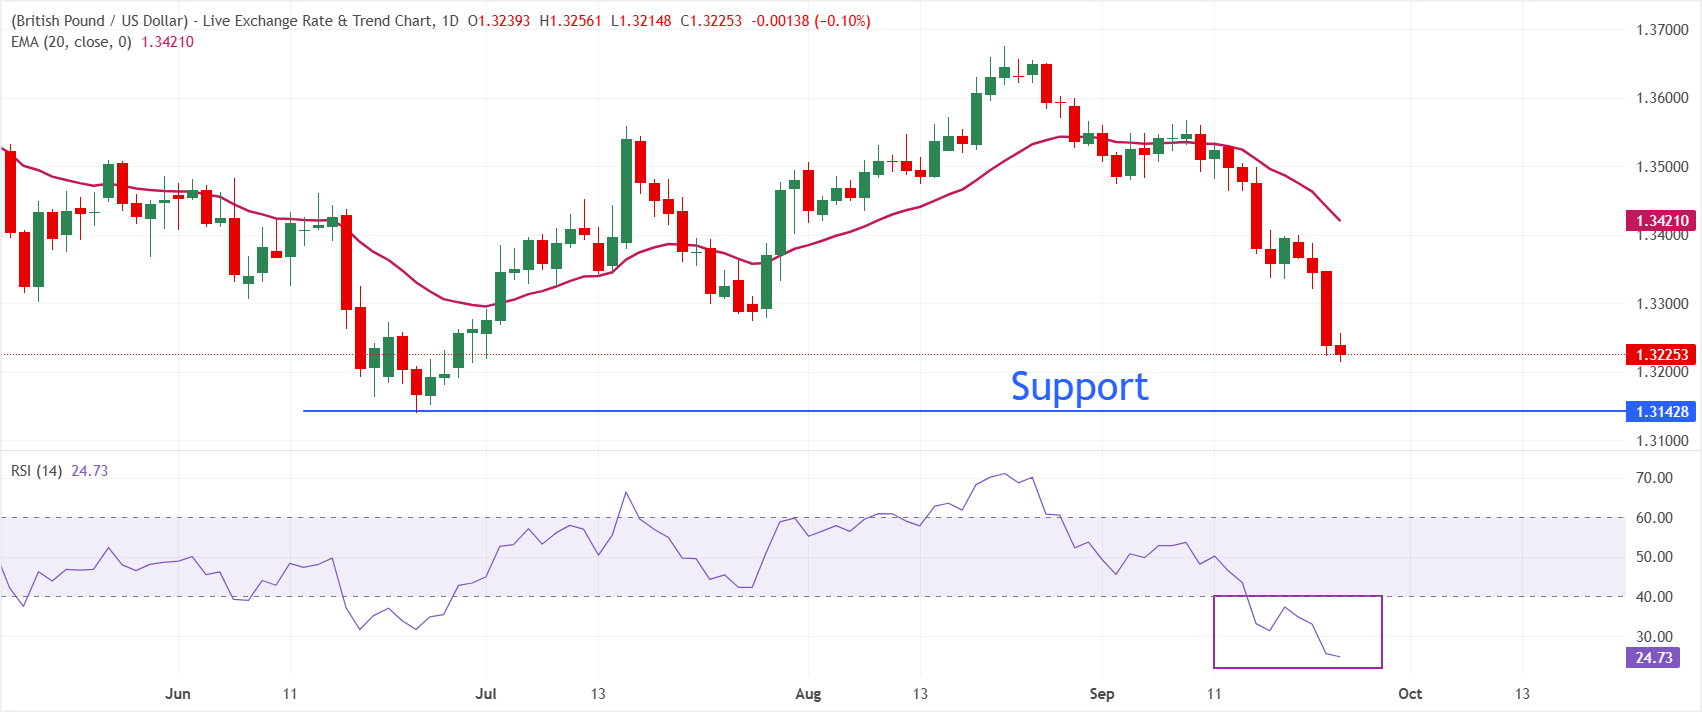
In the daily chart, GBP/USD trades at 1.3225, maintaining a bearish near-term bias as spot remains clearly below the 20-period exponential moving average (EMA) at 1.3421. The pair has extended its retreat from recent highs, and the EMA now acts as immediate overhead supply that caps any recovery attempts, while the Relative Strength Index (14) around 24.7 signals oversold momentum that could slow the downside rather than reverse it outright.
On the topside, initial resistance emerges at the 20-day EMA near 1.3421, and a sustained break above this barrier would be needed to ease the current bearish pressure and allow a more meaningful rebound. Looking down, the pair could extend its decline towards the Year-Till-Date (YTD) low at 1.3140.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.